NEW DELHI: A legal notice issued to PVR INOX over refusal to accept cash at its Ahmedabad multiplex has reignited a debate over whether businesses can insist on digital payments. But the issue needs to be understood beyond the misleading “cash versus UPI” narrative: cash remains legal tender in India, while UPI is a payment system that has emerged as one of Bharat’s most significant technological achievements.
What happened at the PVR INOX outlet?
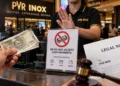
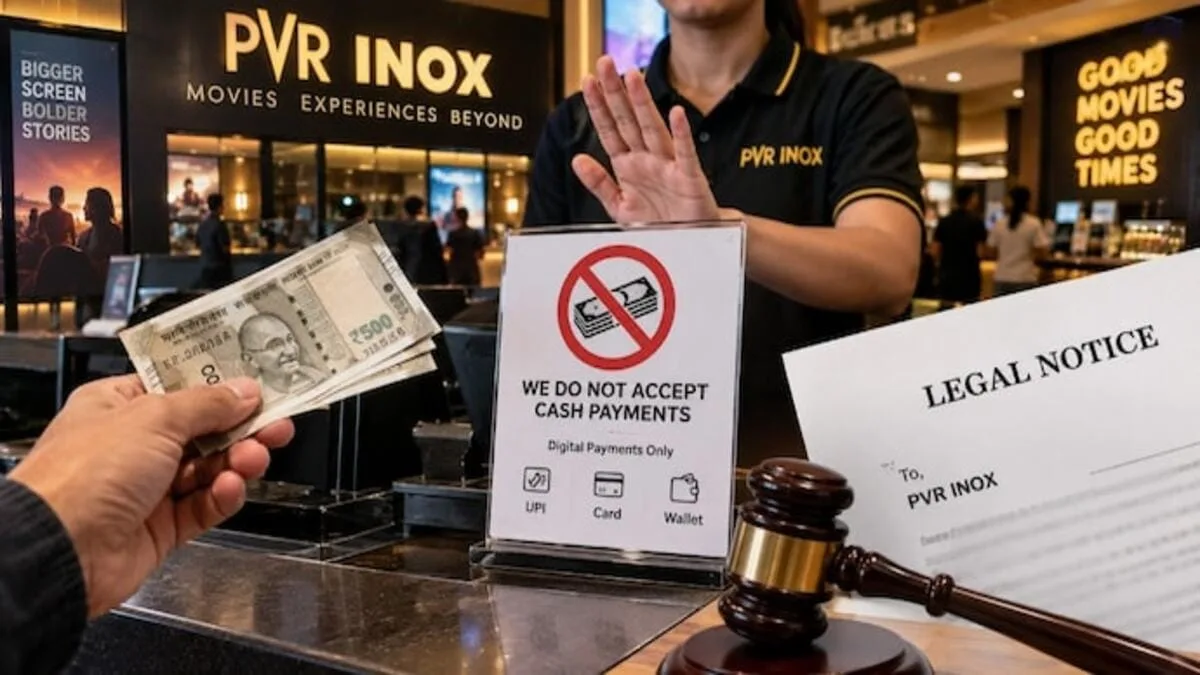
Ahmedabad-based advocate Utkarsh Dave has issued a legal notice to PVR INOX after alleging that the multiplex at Palladium Mall refused to accept cash for his movie ticket and later for food and beverages on September 13.
According to reports, Dave said he was asked to make the payments through UPI and subsequently questioned the legality and transparency of the alleged cashless policy. His notice reportedly cited Section 26(1) of the Reserve Bank of India Act, 1934, and sought clarification on whether the outlet had a formal policy prohibiting cash payments. However, the matter is disputed. A senior PVR INOX official told sources that the company does accept cash and said cash is not refused at its outlets.
The question, therefore, is not simply whether UPI can be used. It is whether a particular business can impose restrictions on payment methods, how those restrictions are communicated and what specific laws apply to the transaction.
Is cash mandatory everywhere?
This is where much of the social-media debate becomes misleading. RBI states that banknotes issued by it and still in circulation are legal tender in India. Section 26 (1) of the RBI Act provides the statutory basis for the legal-tender status of RBI banknotes. But “legal tender” and “every business must accept cash in every commercial situation” are not necessarily interchangeable propositions. However, this does not create an absolute obligation on every private business to accept cash for every transaction.
A business may structure the manner in which it offers a service, subject to applicable laws and regulations. Digital-only transactions are already common in online commerce, app-based services and other settings where the transaction itself is designed around electronic payment.
For physical establishments, however, any restriction on payment methods raises questions of transparency and consumer communication, particularly where customers are informed of the restriction only at the payment counter. That is why the PVR INOX dispute needs to be examined on its specific facts rather than turned into a blanket claim that either “cash must always be accepted” or “businesses can always refuse cash.”
UPI, or the Unified Payments Interface, is a payment infrastructure that allows money to move between participating bank accounts. The rupee remains the underlying currency. This distinction is important because the debate is not really about replacing the rupee with UPI. It is about the different ways in which rupee-denominated payments can be made. A person carrying ₹500 in cash and another person transferring ₹500 through UPI are using different payment mechanisms for the same currency.
UPI has become an important part of India’s payment ecosystem precisely because it offers an interoperable, real-time mechanism for transferring money between participating banks and applications. The International Monetary Fund has described UPI as the world’s largest retail fast-payment system by transaction volume and highlighted interoperability as a key reason for its rapid adoption.
India’s own data shows the scale of the transformation. UPI processed more than 24,162 crore transactions worth around ₹314 lakh crore in FY 2025-26, according to the Union Government. By July 2026, 741 banks were live on the UPI platform. This is not merely a shift from one payment app to another. It represents the creation of a large-scale digital public infrastructure that enables different banks and payment applications to work through an interoperable system.
UPI is a technological achievement of Bharat
The significance of UPI goes beyond everyday QR-code payments. India developed a payment architecture capable of operating at enormous scale while allowing users of different banks and participating applications to transact with one another. That interoperability is one of UPI’s defining features. Unlike closed payment ecosystems in which users may be required to remain within a particular provider’s network, UPI allows participating applications and banks to connect through a common infrastructure. The IMF has specifically identified this interoperability as a major factor behind UPI’s growth.
The achievement is particularly significant because it demonstrates that Bharat can build digital infrastructure for hundreds of millions of users rather than simply import an existing model. UPI has consequently become an important component of India’s Digital Public Infrastructure and a major example of the country’s indigenous digital innovation.
The world is taking notice
UPI’s importance is also increasingly visible outside India. Government data shows that UPI is now operational in multiple foreign markets, including Bhutan, Nepal, Singapore, the UAE, France, Sri Lanka, Mauritius, Qatar, Cambodia and Greece, with the nature of the arrangement varying from country to country.
In some markets, UPI enables Indian travellers to make merchant payments; in others, cross-border remittances or payment-system linkages have been established. In June 2026, UPI acceptance was launched in Cambodia, while UPI-linked cross-border remittances went live with Greece. Cross-border remittances between the Maldives’ Favara system and India’s UPI also became operational in July 2026. This expansion matters because payment infrastructure is increasingly becoming an important part of international economic connectivity.
The PVR INOX controversy should therefore be viewed in its proper context. Cash continues to have legal-tender status in India. At the same time, UPI has transformed how millions of Indians make everyday payments and has developed into a globally recognised real-time payment system. There is no inherent contradiction between these facts.
A customer may prefer cash. Another may prefer UPI. Another may use a card or another digital method. The legal position concerning which modes a particular business must accept depends on the applicable rules and the circumstances of the transaction.
The important requirement is that businesses should communicate payment restrictions clearly, while consumers should not be misled into believing that UPI is either universally mandatory or somehow an illegitimate alternative to cash.
In just a decade, Bharat has built a real-time, interoperable payment infrastructure operating at a scale that has attracted international recognition and adoption. The system is increasingly being connected with payment networks in other countries, creating new possibilities for cross-border payments and local-currency transactions. Therefore, stories around UPI should avoid the simplistic “UPI versus cash” framing.