Representative Image
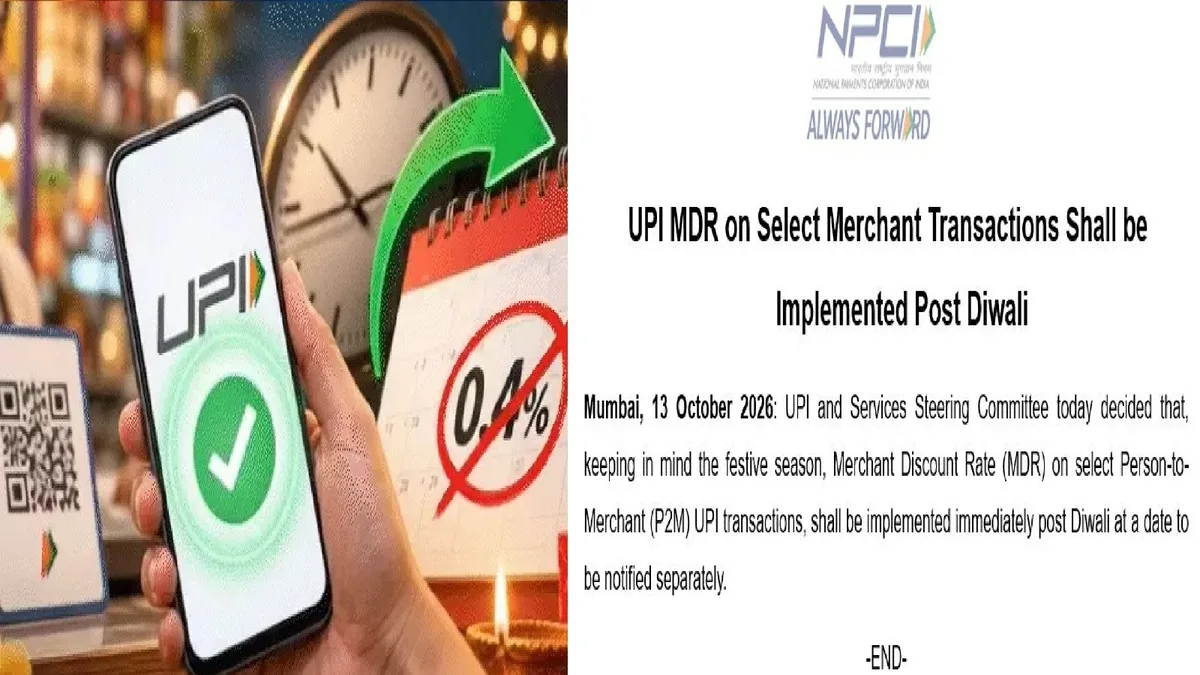
On the cusp of the festive season, the heart of the Indian economy, the National Payments Corporation of India (NPCI) and the Union Government have taken a policy decision that has put a smile on the faces of crores of traders and consumers. The decision to defer until Deepawali the 0.4 per cent Merchant Discount Rate (MDR) on select merchant payments above Rs 2,000, due to come into force on 15 October 2026, is far more than a piece of administrative relief. It is a thoroughly positive and strategic step towards keeping India’s digital backbone strong. The decision has shown that Indian digital policy is not focused solely on raising revenue; it is fully alive to public welfare, Ease of Doing Business and the larger vision of a ‘cashless economy’.
Among the greatest poets the world has known, Mahakavi Kalidasa is famed for an episode from his early life, in which he unwittingly sawed away at the very branch on which he was sitting. When the digital economy is reviewed in modern terms, experts are sometimes haunted by a fear: is the government, too, preparing to take an axe to the very branch of the digital revolution that has given India a unique identity on the global stage? By postponing the 15 October rule, however, the government has shown that its “eyes of policy wisdom” are wide open. It heard and understood, in good time, the concerns of traders, economists and nationwide trade bodies. Deferring the charge just before the festivals demonstrates that the government is thoroughly serious about protecting UPI. It is a positive signal that policymakers are choosing to safeguard the long-term benefits of a vast, transparent Tax Base, which keeps driving the country’s Gross Domestic Product (GDP), rather than recover the immediate ₹20,000 crore infrastructure cost.
Over the past decade, the Unified Payments Interface (UPI) has become far more than a means of transferring money; it is now the biggest catalyst of India’s Socio-Economic Inclusion. The country today has more than 55 crore (550 million) active users, ranging from large malls in the metros to small shopkeepers selling vegetables on the pavements of remote villages.
Historic transaction value: India currently records total UPI transactions of around ₹30 lakh crore every month, a global record.
Contribution of merchant payments: Of the total, payments made to shopkeepers and traders (P2M) amount to roughly Rs 9 lakh crore.
The arithmetic of the proposed charge: The proposed 0.4 per cent charge was to apply only to merchant transactions above Rs 2,000, whose monthly value comes to roughly Rs 6 lakh crore (20 per cent of total UPI transactions). Most importantly, person-to-person (P2P) transactions among the general public, and small merchant payments of up to Rs 2,000, were never to attract any charge, and will not. This is firm proof that the basic infrastructure of digital banking will always remain entirely free and accessible to ordinary citizens.
During Deepawali and Dhanteras, the enthusiasm in Indian markets reaches its peak. This is when record-breaking sales are made of clothing, electronics, household goods, vehicles and gold and silver jewellery. In this festive season, consumers place the greatest trust in the security of UPI rather than carrying cash. Had the 0.4 per cent rule come into force on 15 October, it could have created psychological and technical strain in the markets. Trade bodies such as CAIT and payment gateway companies were quite right to fear that imposing a new rule abruptly could cause several technical difficulties. Traders, afraid of the charge being deducted on large payments, might have started asking customers for cash, leading to long queues at shops and dampening the festive mood.
Thanks to this positive decision by NPCI, ‘digital liquidity’ in the market remains fully secure. Traders are accepting even the largest payments digitally without any financial fear, and there is every hope of new trade records being set during the festivals this year.
Trade interests: a big shield for retailers’ limited margins
The biggest reality of the Indian retail market is that most small and medium traders here operate on very thin Net Profit Margins. The net profit of an average retail shopkeeper typically lies between 3 per cent and 5 per cent. Had an MDR of 0.4 per cent been levied on a large transaction (even with a cap of Rs 300), it would have directly eaten into 10 to 13 per cent of the trader’s total net profit. Small businesses could not have borne such a heavy financial loss. By deferring the decision, the government has given crores of small and medium-scale traders a very large safety net. They can now play their pioneering role in the Digital India campaign without sacrificing their limited profits.
The most positive and far-reaching aspect of this review is that UPI remaining free is directly strengthening the government’s exchequer. When the country’s Informal Economy comes within the ambit of the banking system through digital means, avenues for tax evasion are shut off entirely. If the Centre’s monthly GST collection today stands at an all-time high of Rs 1.8 lakh crore to Rs 2 lakh crore, the transparency brought by UPI is the biggest reason behind it. Digital transactions bring out the true incomes of companies and traders, and as a result the government’s corporate tax and direct income tax collections have also grown manifold.
Had the government insisted on recovering the annual Rs 20,000 crore cost of running the UPI infrastructure, and had even 15 to 20 per cent of digital transactions shifted back to cash, the loss of transparency could have cost it a direct loss of more than ₹50,000 crore in GST and other taxes. Displaying policy foresight, the government has spared itself and the nation’s economy this heavy loss.
Amid this policy relief, a recent research report from IIT Bombay offers the country a highly practical and positive roadmap. The report suggests a revolutionary formula for safeguarding the future of Digital India.
According to the report, a charge of 0.4 per cent is too high for traders. It should be cut to just 0.08 per cent so that no party bears an economic burden. The report establishes that, in the financial year 2026 alone, the country’s banks earned roughly ₹4.85 lakh crore through Current Account and Savings Account (CASA) deposits. Since this money is flowing to banks because of the digital revolution, banks should themselves bear part of the modest cost of running UPI. The study makes clear that India has ample financial capacity to keep its digital infrastructure entirely free and world-class, even without any additional merchant charge.
The most heartening and positive conclusion to emerge from this entire episode is that UPI in India is now being seen as a ‘Digital Public Infrastructure’ (Public Asset) rather than a commercial tool. Just as the government builds National Highways, gleaming railway tracks, modern airports and public parks for the nation’s development, and treats their construction costs as an ‘essential cost of national development’ rather than recovering them directly from the public’s pocket, so too is UPI an essential cost of modern India’s development.
By deferring this charge until Deepawali, the government has sent a clear message that it has left behind the old, slow and opaque era of ‘cash is king’. This historic branch of Digital India will now grow stronger still. The steps policymakers take in future will surely also be decided with the interests of traders and consumers in mind, ensuring that India remains at the forefront of the digital revolution on the global stage.